

Renting vs buying a home in South Africa – and the winner is clear


Buying a home in South Africa is not necessarily the best financial decision, as renting and investing the difference could leave tenants millions of rand better off over a decade.
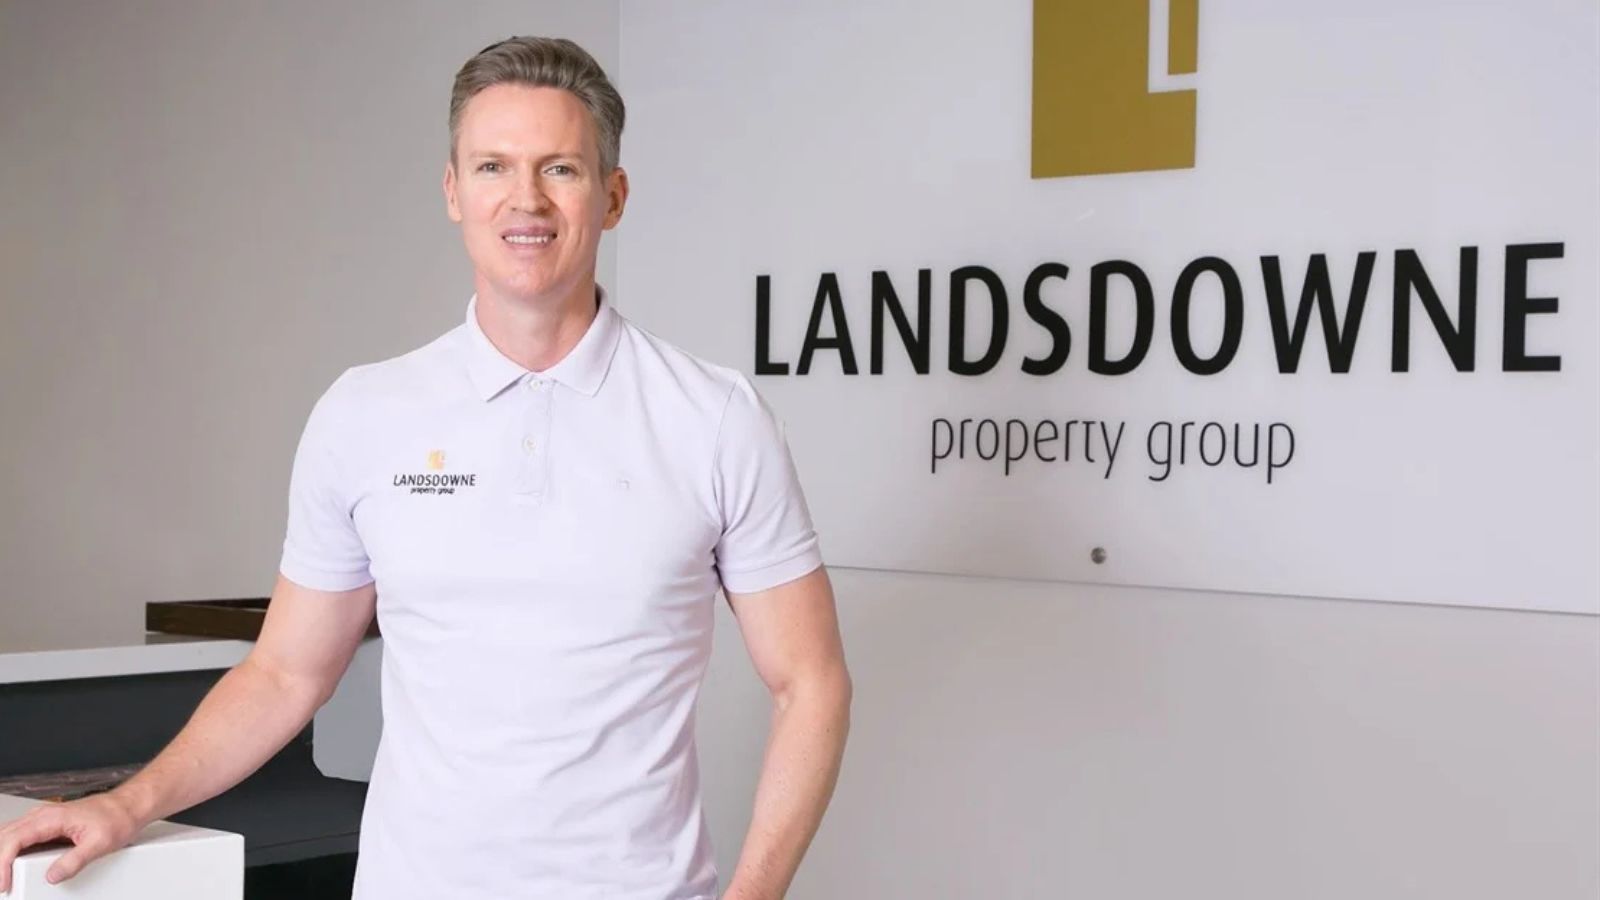
This is the feedback from Jonathan Kohler, founder and CEO of Landsdowne Property Group, who said the decision depends on property prices, rental costs, and expected capital appreciation.
He added that it also depends on whether tenants stay disciplined and invest the money they save by not buying.
“Just because you can afford to buy a property does not necessarily mean you should,” he said.
Kohler said he rented in Johannesburg for much of his career because the numbers made financial sense, and only recently bought a home after he reassessed the market opportunities.
He said renting could remain a sensible wealth-building strategy, provided tenants invested the money they would otherwise have spent on a deposit, transfer costs, and higher monthly ownership expenses.
Kohler made his point by comparing Johannesburg and Cape Town, where property markets have followed different trajectories.
Johannesburg has experienced relatively weak capital appreciation over the years, with some established suburbs offering comparatively affordable properties.
Cape Town has experienced stronger price growth, driven by demand, migration, and limited supply in sought-after areas, but this has made buying more expensive.
In Bryanston, Johannesburg, a four-bedroom family home priced at around R4.5 million could cost approximately R28,000 to R30,000 a month to rent.
Buying the property with a 20% deposit would require a R900,000 upfront payment and a R3.6 million bond over 20 years. At an interest rate of 10.75%, the monthly repayment would be approximately R36,550.
Including rates, insurance, and maintenance estimated at R4,500, the initial monthly cost of ownership would reach R41,050, compared with R30,000 in rent.
The difference is approximately R11,050 per month, excluding the additional capital required for transfer duty, which would amount to about R272,000.
If a tenant invested the deposit, transfer costs and monthly savings, earning an illustrative annual return of 10% before tax and fees, their investments could grow to approximately R4.2 million after ten years.
Discipline is key
By comparison, a homeowner would have built equity through bond repayments, but assuming annual property appreciation of 2% and selling costs of 5%, their net equity would amount to around R2.5 million.
Under these assumptions, renting and investing would leave the tenant approximately R1.6 million better off.
The property would need to appreciate by around 5.6% annually for buying to produce a comparable financial outcome.
Cape Town presents a different picture, but buying is not necessarily the clear winner there either.
A three-bedroom home in Claremont priced at R5.5 million could be rented for approximately R35,000 a month. With a 20% deposit, the buyer would need a R4.4 million bond, costing around R44,670 monthly.
Adding estimated rates, insurance, and maintenance of R5,500 takes ownership costs to approximately R50,170, or R15,170 more than renting.
The deposit would be R1.1 million, while transfer duty would be approximately R382,000. Investing this capital and the monthly savings could generate around R4.8 million after ten years.
The homeowner’s net equity would be approximately R3.7 million if prices rose by 3% annually, or R5.2 million if prices rose by 5% annually.
Buying would only outperform renting and investing if annual property appreciation reached approximately 4.4% in this example.
Kohler cautioned against assuming Cape Town’s exceptional property growth would continue indefinitely, noting that some outlying areas were taking longer to attract tenants.
Kohler said his decision to buy reflected his view that value was emerging in parts of Johannesburg, rather than a belief that homeownership was always financially superior.
The calculations, however, depend heavily on tenants investing their savings. Someone who spends the difference between rent and ownership costs will not build the alternative wealth assumed in the comparison.
Buying also offers stability, security and forced savings through bond repayments, which may matter more to families planning to stay in the same home for many years.
Kohler said the decision should come down to the cost of ownership compared with rent, expected property appreciation and the discipline to invest the difference.
The table below outlines the financial gains from renting vs buying in both Johannesburg and Cape Town.
| Assumption | Bryanston (Johannesburg) | Claremont (Cape Town) |
| Property Type | 4-bedroom family home | 3-bedroom home |
| Purchase Price | R4,500,000 | R5,500,000 |
| Deposit (20%) | R900,000 | R1,100,000 |
| Transfer Duty (SARS) | ~R272,000 | ~R382,000 |
| Upfront Capital Retained by Tenant | ~R1,172,000 | ~R1,482,000 |
| Bond Amount (20 yrs @ 10.75% prime) | R3,600,000 | R4,400,000 |
| Monthly Bond Repayment | ~R36,550 | ~R44,670 |
| Monthly Rates, Insurance & Maintenance | ~R4,500 | ~R5,500 |
| Total Initial Monthly Ownership Cost | ~R41,050 | ~R50,170 |
| Comparable Monthly Rent | ~R30,000 (range: R28k–R30k) | ~R35,000 |
| Initial Monthly Savings (Renting) | ~R11,050 | ~R15,170 |
| Tenant Investment Value (after 10 yrs) | ~R4,200,000 | ~R4,800,000 |
| Buyer Net Equity (after 10 yrs) | ~R2,500,000 (at 2% annual growth) | ~R3,700,000 (at 3% growth) / ~R5,200,000 (at 5% growth) |
| 10-Year Financial Advantage | Renting by ~R1,600,000 | Renting by ~R1,100,000 (at 3% growth) |
| Break-Even Annual Property Growth | ~5.6% per year | ~4.4% per year |
• Tenant Investment Return: 10% per annum (before tax and fees), investing the upfront deposit, saved transfer duty, and evolving monthly cash-flow difference.
• Cost Escalation: Both rent and ownership running costs (rates, insurance, maintenance) increase by 5% per annum.
• Interest Rate: The prime lending rate remains fixed at 10.75% over the 10 years.
• Selling Costs: Buyer’s net equity after 10 years deducts the remaining bond balance and an estimated 5% in selling costs.



 Loading ...