

What investors can expect for the rest of 2026


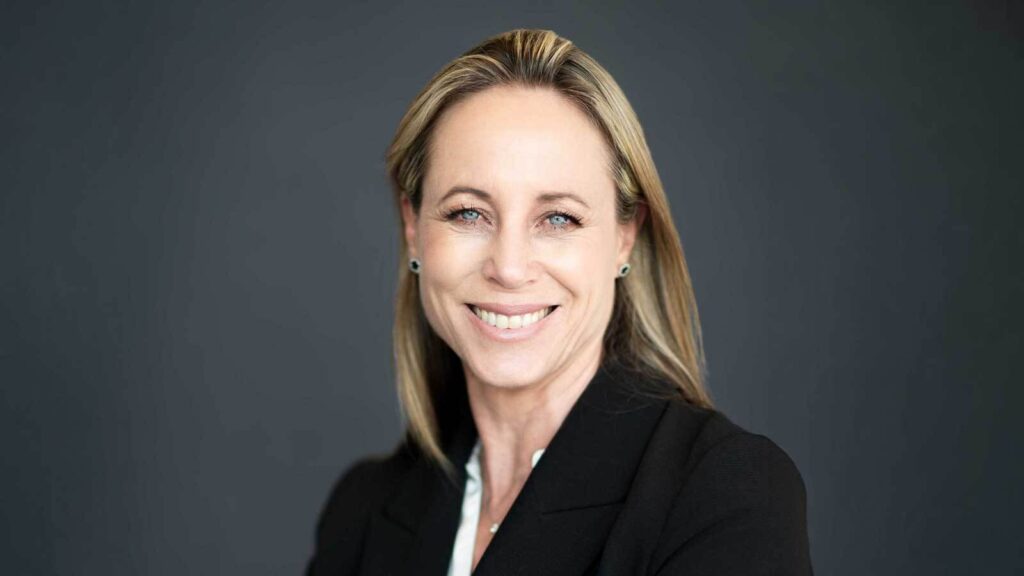
By Kim Zietsman, Laurium Capital.
South African investors entered the final quarter of 2026 in a very different frame of mind from a year ago.
At the same point in 2025, domestic equities had delivered strong gains and portfolios broadly reflected the improving mood.
This year has been more demanding: returns from the local equity market have been uneven, and September’s sharp setback left many investors feeling considerably less enthusiastic.
That contrast is a useful reminder that markets rarely move in a straight line.
A strong year can be followed by a period of consolidation, while uncomfortable conditions can create the valuations from which future returns are generated.
The question for investors is therefore not simply whether the next three months will be positive, but which forces are most likely to shape markets and how portfolios should be positioned for a range of outcomes.
A tougher global backdrop
September illustrated how quickly the global backdrop can change.
Inflation concerns, tighter monetary policy expectations and renewed geopolitical tension pushed government bond yields sharply higher.
The US Federal Reserve raised rates by 25 basis points, while the European Central Bank also tightened policy.
The US 10-year Treasury yield ended the month at 5.29%, a level last seen in the early 2000s placing pressure on bonds and equity valuations alike.
Energy markets added another layer of uncertainty.
Brent crude closed September above US$100 a barrel as conflict involving Iran affected supply expectations.
Higher oil prices, combined with stretched refining costs complicate the inflation outlook, with fuel prices stubbornly high, delay the prospect of meaningful interest-rate relief and raise costs for households and businesses.
For the remainder of the year, investors should expect markets to remain highly sensitive to inflation data, central-bank guidance, the path of oil prices, refining costs and geopolitical headlines.
South Africa’s key fourth-quarter events
Locally, two events will command particular attention.
The first is the Medium-Term Budget Policy Statement on 21 October.
Investors will look for evidence that government remains committed to fiscal discipline, debt stabilisation and structural reform.
Revenue performance, spending pressures, the public-sector wage bill and support for state-owned entities will all matter for confidence in South African bonds, the rand and domestically focused shares.
The second is the local government election on 4 November.
Municipal elections do not normally determine national economic policy, but this one will be closely watched because it is the first local poll since the formation of the Government of National Unity.
The results may reshape control of major metros, increase the importance of coalition arrangements and influence perceptions of political stability and service delivery.
Markets will be less interested in the campaign noise than in whether the outcome supports workable administrations and continued reform.
Why local equities have disappointed
The JSE’s weak September performance was unusually concentrated.
The Capped All Share Index fell 5.8% in rand terms – its fifth-worst month in the past decade- with gold miners and Naspers among the largest detractors.
Gold Fields (-19.4%) and AngloGold Ashanti (-14.5%) alone accounted for roughly 2.2 percentage points of the decline.
By contrast, a small number of domestically oriented companies – including tertiary education provider Stadio Holdings (+28.8%) Shoprite, Discovery and Remgro – managed modest gains, while Sasol rose strongly.
The dispersion reinforces the value of active stock selection.
Investors should not assume that a difficult index automatically means every South African business is deteriorating, or that last year’s winners will continue to lead.
Valuation offers some support
Despite the more subdued return experience, the local market is not without opportunity.
South African equities have de-rated significantly.
Laurium Capital’s proprietary Domestic SA Index, which tracks companies with meaningful exposure to the local economy, trades at about 9.5 times forward earnings.
That valuation reflects considerable caution.
If inflation stabilises, fiscal credibility is maintained, election outcomes prove manageable or economic reforms gain traction, a number of shares are positioned to respond meaningfully.
The fixed-income picture is also nuanced.
The South African Reserve Bank raised the repo rate by 25 basis points to 7.25% in September as it responded to elevated inflation risks.
Government bond yields moved higher alongside global markets, with the 10-year yield approaching 9%, while the All Bond Index was flat for the month.
High starting yields can provide attractive income, but investors must remain alert to oil prices, inflation, fiscal risk and global rate volatility.
How investors should approach the final quarter
Investors should resist the temptation to turn a disappointing period into a wholesale change of strategy.
The remaining months of 2026 are likely to be volatile, but volatility is not the same as permanent loss.
A diversified portfolio – across local and global equities, fixed income, cash and appropriate alternatives – remains the most reliable defence against uncertainty.
Within South African equities, selectivity is critical.
Investors should favour companies with resilient balance sheets, credible management teams and the ability to grow earnings through a difficult environment.
They should also retain enough flexibility to add exposure when market dislocations place good businesses on more attractive valuations.
Last year’s strong returns made investing feel easier than it does today.
Yet periods of lower confidence often create the foundations for better future returns.
The final quarter will bring significant tests – from global rates and geopolitics to the mini-budget and municipal elections – but it will also give investors clearer signals about South Africa’s policy direction and the earnings potential embedded in a discounted market.
Patience, diversification and disciplined active management will matter more than trying to predict each headline.
Learn more about Laurium Capital.
Laurium Capital is an authorised financial services provider (FSP 34142).
This article is published for information purposes and does not constitute financial advice. Past performance is not necessarily a guide to future performance. Investors should consider their individual circumstances and seek appropriate professional advice.



 Loading ...